R.S. No.46/3 (Matharasa ismail, Kumbakonam) Property
Thanjavur
District
Kumbakonam
Taluk
Kallur
Village
-
Town
-
ward
-
Block
Rural
Rural/Urban
-
O.S. No.
46
R.S. No.
3
S.D. No.
370
Patta Number
4250 sq.m.
Extent
A-Register
| 1. புல எண் | 46 | 10. மண் வயனமும் ரகமும் | 1 - 2 |
| 2. உட்பிரிவு எண் | 3 | 11. மண் தரம் | 4 |
| 3. பழைய புல உட்பிரிவு எண் | 46-3 | 12. தீர்வை (ரூ - ஹெ) | 26.24 |
| 4. பகுதி | - | 13. பரப்பு (ஹெக்டேர் - ஏர்) | 0 - 42.50 |
| 5. அரசு / ரயத்துவாரி ரயத்துவாரி | ரயத்துவாரி | 14. மொத்த தீர்வை (ரூ - பை) | 11.15 |
| 6. நிலத்தின் வகை நஞ்சை | நஞ்சை | 15. பட்டா எண் | 370 |
| 7. பாசன ஆதாரம் A | B | 16. இரு போகமா | - |
| 8. குறிப்பு | - | ||
| 9. பெயர் | 1.மேலக்காவேரி மதரஸா டிரஸ்டி ... - | ||

1. மேற்கண்ட தகவல் / சான்றிதழ் நகல் விவரங்கள் தமிழ் நிலம் மென்பொருளில் இருந்து (https://eservices.tn.gov.in) பெறப்பட்டவை.
2. இத் தகவல்கள் 28/09/2024அன்று 02:54:32 PM நேரத்தில் அச்சடிக்கப்பட்டது.
Patta Details
| வ.எண் | புல எண் | உட்பிரிவு எண் | புன்செய் | நன்செய் | மற்றவை | குறிப்புரைகள் | |||
|---|---|---|---|---|---|---|---|---|---|
| பரப்பு | தீர்வை | பரப்பு | தீர்வை | பரப்பு | தீர்வை | ||||
| ஹெக் - ஏர் | ரூ - பை | ஹெக் - ஏர் | ரூ - பை | ஹெக் - ஏர் | ரூ - பை | ||||
| 1 | 77 | 2 | 0 - 1.50 | 0.14 | -- | -- | -- | -- | -- |
| 2 | 233 | 6 | 0 - 8.50 | 0.63 | -- | -- | -- | -- | -- |
| 3 | 293 | 4 | 0 - 11.50 | 1.33 | -- | -- | -- | -- | -- |
| 4 | 11 | 3A | -- | -- | 0 - 45.50 | 19.93 | -- | -- | -- |
| 5 | 64 | 5 | -- | -- | 0 - 25.00 | 6.58 | -- | -- | -- |
| 6 | 277 | 2 | -- | -- | 0 - 13.00 | 3.04 | -- | -- | -- |
| 7 | 319 | 8A | -- | -- | 0 - 5.00 | 1.27 | -- | -- | -- |
| 8 | 8 | 9 | 0 - 1.00 | 0.14 | -- | -- | -- | -- | -- |
| 9 | 8 | 16 | 0 - 1.50 | 0.19 | -- | -- | -- | -- | -- |
| 10 | 9 | 9 | 0 - 1.00 | 0.14 | -- | -- | -- | -- | -- |
| 11 | 12 | 9 | 0 - 2.50 | 0.21 | -- | -- | -- | -- | -- |
| 12 | 18 | 7 | 0 - 3.50 | 0.32 | -- | -- | -- | -- | -- |
| 13 | 18 | 9 | 0 - 1.50 | 0.14 | -- | -- | -- | -- | -- |
| 14 | 18 | 11 | 0 - 2.50 | 0.21 | -- | -- | -- | -- | -- |
| 15 | 18 | 12 | 0 - 6.00 | 0.53 | -- | -- | -- | -- | -- |
| 16 | 19 | 5 | 0 - 3.00 | 0.25 | -- | -- | -- | -- | -- |
| 17 | 40 | 2 | 0 - 1.50 | 0.19 | -- | -- | -- | -- | -- |
| 18 | 87 | 2 | 0 - 2.50 | 0.21 | -- | -- | -- | -- | -- |
| 19 | 87 | 13 | 0 - 6.00 | 0.53 | -- | -- | -- | -- | -- |
| 20 | 87 | 12 | 0 - 11.50 | 1.02 | -- | -- | -- | -- | -- |
| 21 | 102 | 1 | 0 - 7.00 | 0.60 | -- | -- | -- | -- | -- |
| 22 | 102 | 3 | 0 - 8.50 | 0.74 | -- | -- | -- | -- | -- |
| 23 | 119 | 22 | 0 - 10.00 | 0.81 | -- | -- | -- | -- | -- |
| 24 | 121 | 3 | 0 - 3.00 | 0.25 | -- | -- | -- | -- | -- |
| 25 | 126 | 5 | 0 - 8.50 | 0.74 | -- | -- | -- | -- | -- |
| 26 | 126 | 6 | 0 - 4.50 | 0.39 | -- | -- | -- | -- | -- |
| 27 | 201 | 3 | 0 - 13.00 | 0.76 | -- | -- | -- | -- | -- |
| 28 | 231 | 2 | 0 - 7.50 | 0.54 | -- | -- | -- | -- | -- |
| 29 | 235 | 3 | 0 - 6.50 | 0.48 | -- | -- | -- | -- | -- |
| 30 | 235 | 4 | 0 - 5.50 | 0.39 | -- | -- | -- | -- | -- |
| 31 | 251 | 8 | 0 - 12.50 | 0.93 | -- | -- | -- | -- | -- |
| 32 | 256 | 9 | 0 - 11.00 | 0.81 | -- | -- | -- | -- | -- |
| 33 | 267 | 9 | 0 - 15.00 | 0.88 | -- | -- | -- | -- | -- |
| 34 | 277 | 1 | 0 - 10.00 | 0.59 | -- | -- | -- | -- | -- |
| 35 | 279 | 2 | 0 - 4.00 | 0.24 | -- | -- | -- | -- | -- |
| 36 | 281 | 3 | 0 - 14.00 | 0.83 | -- | -- | -- | -- | -- |
| 37 | 293 | 2 | 0 - 21.00 | 2.47 | -- | -- | -- | -- | -- |
| 38 | 297 | 4 | 0 - 17.50 | 2.04 | -- | -- | -- | -- | -- |
| 39 | 311 | 5 | 0 - 9.50 | 0.72 | -- | -- | -- | -- | -- |
| 40 | 313 | 2 | 0 - 22.50 | 1.65 | -- | -- | -- | -- | -- |
| 41 | 314 | 1 | 0 - 13.00 | 0.96 | -- | -- | -- | -- | -- |
| 42 | 323 | 7 | 0 - 6.00 | 0.36 | -- | -- | -- | -- | -- |
| 43 | 9 | 1 | -- | -- | 0 - 26.50 | 6.90 | -- | -- | -- |
| 44 | 22 | 5 | -- | -- | 0 - 54.50 | 14.44 | -- | -- | -- |
| 45 | 35 | 1 | -- | -- | 0 - 18.00 | 4.67 | -- | -- | -- |
| 46 | 39 | 3 | -- | -- | 1 - 4.00 | 27.29 | -- | -- | -- |
| 47 | 40 | 1 | -- | -- | 0 - 53.50 | 14.02 | -- | -- | -- |
| 48 | 40 | 3 | -- | -- | 0 - 13.00 | 3.40 | -- | -- | -- |
| 49 | 46 | 3 | -- | -- | 0 - 42.50 | 11.15 | -- | -- | -- |
| 50 | 62 | 3A | -- | -- | 0 - 52.50 | 13.80 | -- | -- | -- |
| 51 | 67 | 1B | -- | -- | 0 - 32.00 | 8.38 | -- | -- | -- |
| 52 | 76 | 2A | -- | -- | 0 - 7.00 | 1.80 | -- | -- | -- |
| 53 | 76 | 4A | -- | -- | 0 - 43.00 | 11.25 | -- | -- | -- |
| 54 | 80 | 10 | -- | -- | 0 - 10.00 | 2.66 | -- | -- | -- |
| 55 | 82 | 1 | -- | -- | 0 - 17.00 | 4.46 | -- | -- | -- |
| 56 | 83 | 18 | -- | -- | 0 - 1.00 | 0.21 | -- | -- | -- |
| 57 | 83 | 22 | -- | -- | 0 - 1.50 | 0.42 | -- | -- | -- |
| 58 | 83 | 23 | -- | -- | 0 - 1.00 | 0.21 | -- | -- | -- |
| 59 | 84 | 10 | -- | -- | 0 - 13.50 | 4.15 | -- | -- | -- |
| 60 | 92 | 4 | -- | -- | 0 - 18.50 | 4.89 | -- | -- | -- |
| 61 | 107 | 6 | -- | -- | 0 - 17.50 | 4.09 | -- | -- | -- |
| 62 | 107 | 7 | -- | -- | 0 - 42.50 | 10.07 | -- | -- | -- |
| 63 | 108 | 1 | -- | -- | 1 - 31.00 | 30.69 | -- | -- | -- |
| 64 | 113 | 2 | -- | -- | 0 - 25.50 | 5.99 | -- | -- | -- |
| 65 | 124 | 4 | -- | -- | 0 - 10.00 | 2.66 | -- | -- | -- |
| 66 | 122 | 2 | -- | -- | 0 - 12.00 | 3.19 | -- | -- | -- |
| 67 | 124 | 13 | -- | -- | 0 - 15.50 | 4.04 | -- | -- | -- |
| 68 | 133 | 2 | -- | -- | 0 - 16.00 | 4.25 | -- | -- | -- |
| 69 | 145 | 2 | -- | -- | 0 - 85.50 | 22.62 | -- | -- | -- |
| 70 | 149 | 2B | -- | -- | 0 - 48.00 | 12.52 | -- | -- | -- |
| 71 | 151 | 4 | -- | -- | 0 - 45.50 | 12.00 | -- | -- | -- |
| 72 | 153 | 1 | -- | -- | 0 - 50.50 | 13.28 | -- | -- | -- |
| 73 | 162 | 1 | -- | -- | 0 - 98.50 | 25.91 | -- | -- | -- |
| 74 | 208 | 4 | -- | -- | 0 - 5.50 | 1.33 | -- | -- | -- |
| 75 | 233 | 8 | -- | -- | 0 - 51.00 | 13.49 | -- | -- | -- |
| 76 | 235 | 9 | -- | -- | 0 - 25.00 | 6.58 | -- | -- | -- |
| 77 | 236 | 4 | -- | -- | 0 - 5.00 | 1.27 | -- | -- | -- |
| 78 | 236 | 11 | -- | -- | 0 - 9.50 | 2.44 | -- | -- | -- |
| 79 | 237 | 17 | -- | -- | 0 - 1.50 | 0.42 | -- | -- | -- |
| 80 | 238 | 4 | -- | -- | 0 - 41.50 | 10.94 | -- | -- | -- |
| 81 | 238 | 5 | -- | -- | 0 - 43.50 | 11.47 | -- | -- | -- |
| 82 | 239 | 2 | -- | -- | 0 - 95.00 | 24.85 | -- | -- | -- |
| 83 | 244 | 2 | -- | -- | 0 - 47.00 | 12.32 | -- | -- | -- |
| 84 | 246 | 8 | -- | -- | 0 - 7.50 | 1.91 | -- | -- | -- |
| 85 | 246 | 9 | -- | -- | 0 - 7.50 | 1.91 | -- | -- | -- |
| 86 | 255 | 3 | -- | -- | 0 - 44.50 | 11.68 | -- | -- | -- |
| 87 | 259 | 1 | -- | -- | 0 - 45.50 | 12.00 | -- | -- | -- |
| 88 | 260 | 1 | -- | -- | 0 - 50.00 | 13.17 | -- | -- | -- |
| 89 | 268 | 10 | -- | -- | 0 - 4.50 | 1.05 | -- | -- | -- |
| 90 | 268 | 11 | -- | -- | 0 - 11.50 | 2.66 | -- | -- | -- |
| 91 | 270 | 4 | -- | -- | 0 - 63.00 | 14.73 | -- | -- | -- |
| 92 | 273 | 1 | -- | -- | 0 - 41.50 | 9.69 | -- | -- | -- |
| 93 | 277 | 5 | -- | -- | 1 - 11.50 | 29.31 | -- | -- | -- |
| 94 | 277 | 6 | -- | -- | 0 - 45.50 | 12.00 | -- | -- | -- |
| 95 | 281 | 9 | -- | -- | 0 - 5.00 | 1.14 | -- | -- | -- |
| 96 | 282 | 7 | -- | -- | 0 - 11.00 | 2.57 | -- | -- | -- |
| 97 | 302 | 1 | -- | -- | 0 - 50.00 | 13.06 | -- | -- | -- |
| 98 | 313 | 1B | -- | -- | 0 - 12.50 | 3.17 | -- | -- | -- |
| 99 | 316 | 9A | -- | -- | 0 - 0.50 | 0.11 | -- | -- | -- |
| 100 | 319 | 16A | -- | -- | 0 - 8.50 | 2.25 | -- | -- | -- |
| 101 | 326 | 3 | -- | -- | 0 - 44.50 | 11.68 | -- | -- | -- |
| Total | 2 - 95.5 | -- | 20 - 84.5 | -- | -- | -- | -- | ||

1. மேற்கண்ட தகவல் / சான்றிதழ் நகல் விவரங்கள் தமிழ் நிலம் மென்பொருளில் இருந்து (https://eservices.tn.gov.in) பெறப்பட்டவை.
2. இத் தகவல்கள் 28/09/2024அன்று 04:16:27 PM நேரத்தில் அச்சடிக்கப்பட்டது.
3. கைப்பேசி கேமராவின் 2D barcode படிப்பான் மூலம் படித்து 3G/GPRS வழி இணையதளத்தில் சரிபார்க்கவும்.
Need Complete Property Verification?
Get ownership details, EC records, FMB, zone checks, geo-insights & AI analysis - all in one place


Understanding WAQF Land Property in Kallur, Thanjavur: A Comprehensive Guide
The WAQF System and Principles of Islamic Endowment
WAQF, an Arabic term meaning "confinement" or "dedication," is a form of Islamic endowment where a property or asset is set aside permanently for religious or charitable purposes. This system is deeply rooted in Islamic principles, promoting the welfare of the community while ensuring the preservation of assets for future generations. Once a property is declared as WAQF, it cannot be sold, gifted, or inherited, as its ownership is transferred to Allah, with its benefits earmarked for specific purposes such as education, healthcare, or religious activities.
The WAQF property located in Kallur, Thanjavur, is a significant example of this enduring tradition. Registered under WAQF ID 483, this rural land spans 4250 sq.m, serving as an asset dedicated to the betterment of the community and the preservation of Islamic heritage.
The Legal Framework Governing WAQF Properties
WAQF properties in India are governed by the provisions of the Waqf Act, 1995, which ensures their protection, regulation, and administration. The Act establishes State WAQF Boards entrusted with the oversight of WAQF assets, addressing grievances, and ensuring that these properties are utilized for their intended purposes.
In the case of the Kallur WAQF land, the Tamil Nadu WAQF Board is responsible for its management, ensuring that it adheres to the objectives set forth at the time of its endowment. This legal framework not only protects the property from encroachment or misuse but also streamlines its administration for the community’s benefit.
Land Records and Documentation: Importance and Relevance
Proper documentation is key to the transparent and effective management of WAQF properties. The Kallur WAQF land is identified through various official records, including its survey number (New: 46, Subdivision: 3) and patta number (370). These records serve as legal proof of ownership, classification, and extent of the property, which is crucial for its administration and dispute resolution.
Maintaining updated land records ensures that WAQF properties are protected against illegal claims and encroachments. For the Kallur property, its total extent of 4250 sq.m is clearly documented, emphasizing the importance of accurate records in preserving this valuable asset for generations.
Survey Numbers: Identifying WAQF Properties
Survey numbers are essential tools for identifying and demarcating land parcels. The Kallur WAQF property, with its survey number 46 and subdivision 3, allows for precise mapping and categorization of the land. This not only aids in administrative processes but also ensures clarity in ownership and usage rights.
Survey numbers also play a critical role in land audits and inspections conducted by the WAQF Board. They provide a foundation for legal claims and help in resolving disputes, ensuring that the property remains safeguarded under the WAQF system.
Community Welfare and Religious Purposes
One of the primary objectives of WAQF properties is to serve the community. The Kallur WAQF land, classified as rural, holds immense potential to support various initiatives aimed at improving the quality of life for local residents. From establishing schools and healthcare facilities to supporting mosques and religious institutions, WAQF properties are instrumental in promoting social and spiritual well-being.
In addition to its developmental role, the Kallur WAQF property contributes to preserving the Islamic cultural and religious heritage of the region, serving as a testament to the enduring values of charity and community service.
WAQF Board Administration and Oversight
The Tamil Nadu WAQF Board plays a pivotal role in the management and oversight of the Kallur WAQF property. Its responsibilities include maintaining records, ensuring compliance with legal requirements, and monitoring the property’s utilization for its intended purposes. The Board also addresses grievances and works to resolve disputes related to WAQF properties.
Regular inspections, audits, and consultations with local stakeholders are conducted to ensure transparent and effective administration. This oversight is critical in maintaining the integrity and purpose of the WAQF endowment in Kallur.
Heritage Preservation and Maintenance
WAQF properties are not just assets; they are legacies that reflect the rich history and cultural heritage of the Islamic community. The Kallur WAQF land in Thanjavur is a part of this legacy, requiring careful preservation and maintenance to honor its historical and spiritual significance.
The WAQF Board collaborates with local authorities and community members to ensure the upkeep of such properties. Initiatives may include landscaping, fencing, and protecting the land from encroachments or environmental degradation. These efforts ensure that the property remains a valuable resource for future generations.
Legal Protections and Property Rights
WAQF properties in India enjoy strong legal protections under the Waqf Act, 1995. These protections ensure that the property cannot be sold, misused, or encroached upon, safeguarding its purpose as an endowment. The Kallur WAQF land is no exception, with its classification and documentation reinforcing its status as a protected asset.
In cases of disputes or illegal activities, the WAQF Board has the authority to take legal action, ensuring the property’s rights are upheld. This legal framework not only secures the property but also instills confidence among the community in the WAQF system’s integrity and purpose.
Conclusion
The WAQF property in Kallur, Thanjavur, is a symbol of the Islamic tradition of charity and community welfare. Spanning 4250 sq.m, this rural land is a vital asset that serves religious, charitable, and social purposes. Through the efforts of the Tamil Nadu WAQF Board and adherence to the Waqf Act, 1995, the property remains protected and preserved for the benefit of the community.
Understanding the significance of WAQF properties, such as the Kallur land, highlights the importance of proper documentation, legal protections, and community involvement in sustaining these endowments. As a cornerstone of Islamic heritage, WAQF properties continue to play a crucial role in fostering social harmony and uplifting the underprivileged, ensuring their lasting impact for generations to come.


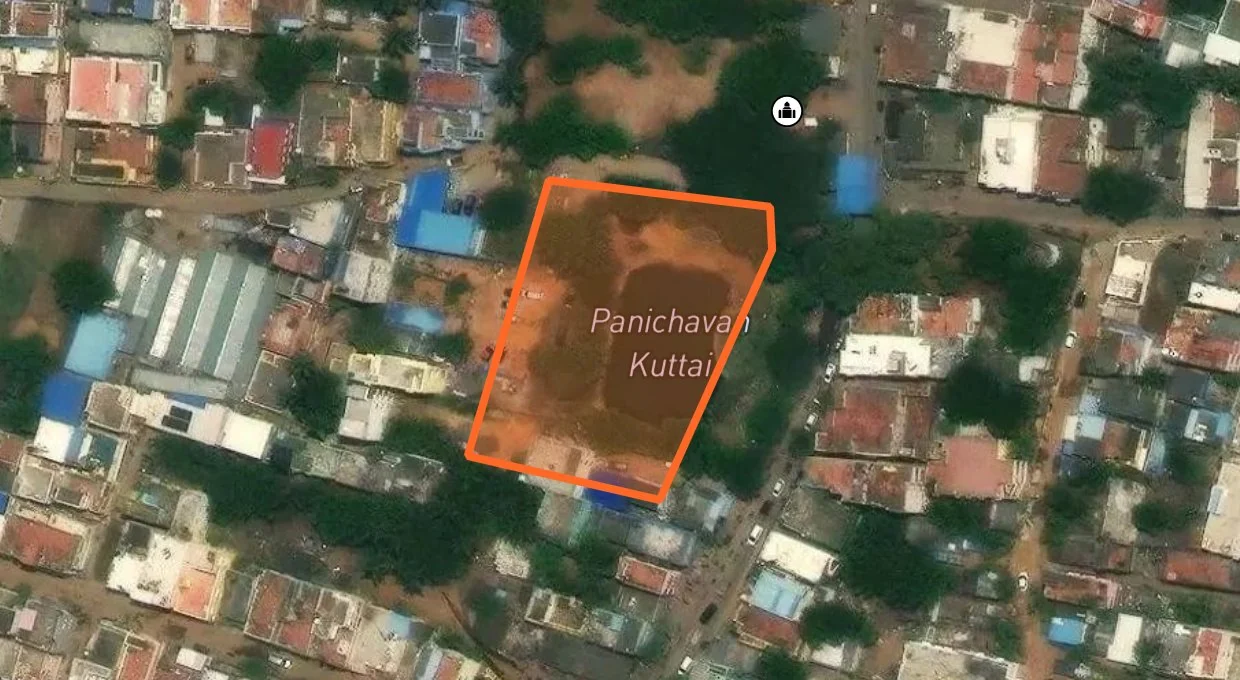
Ask the records, or walk the map.
LandLens One answers from Tamil Nadu land law itself, cited to the page, then acts on the registers. One Map lights them up on the parcel. Your history stays in one place across both.
YOU APPROVE ANY SPEND
A customer has just used our Building Plan Approval Services
1 hour ago
