R.S. No.260/1 (Matharasa ismail, Kumbakonam) Property
Thanjavur
District
Kumbakonam
Taluk
Kallur
Village
-
Town
-
ward
-
Block
Rural
Rural/Urban
-
O.S. No.
260
R.S. No.
1
S.D. No.
370
Patta Number
5000 sq.m.
Extent
A-Register
| 1. புல எண் | 260 | 10. மண் வயனமும் ரகமும் | 1 - 2 |
| 2. உட்பிரிவு எண் | 1 | 11. மண் தரம் | 4 |
| 3. பழைய புல உட்பிரிவு எண் | 260-1 | 12. தீர்வை (ரூ - ஹெ) | 26.24 |
| 4. பகுதி | - | 13. பரப்பு (ஹெக்டேர் - ஏர்) | 0 - 50.00 |
| 5. அரசு / ரயத்துவாரி ரயத்துவாரி | ரயத்துவாரி | 14. மொத்த தீர்வை (ரூ - பை) | 13.17 |
| 6. நிலத்தின் வகை நஞ்சை | நஞ்சை | 15. பட்டா எண் | 370 |
| 7. பாசன ஆதாரம் A | C | 16. இரு போகமா | - |
| 8. குறிப்பு | - | ||
| 9. பெயர் | 1.மேலக்காவேரி மதரஸா டிரஸ்டி ... - | ||

1. மேற்கண்ட தகவல் / சான்றிதழ் நகல் விவரங்கள் தமிழ் நிலம் மென்பொருளில் இருந்து (https://eservices.tn.gov.in) பெறப்பட்டவை.
2. இத் தகவல்கள் 28/09/2024அன்று 02:54:59 PM நேரத்தில் அச்சடிக்கப்பட்டது.
Patta Details
| வ.எண் | புல எண் | உட்பிரிவு எண் | புன்செய் | நன்செய் | மற்றவை | குறிப்புரைகள் | |||
|---|---|---|---|---|---|---|---|---|---|
| பரப்பு | தீர்வை | பரப்பு | தீர்வை | பரப்பு | தீர்வை | ||||
| ஹெக் - ஏர் | ரூ - பை | ஹெக் - ஏர் | ரூ - பை | ஹெக் - ஏர் | ரூ - பை | ||||
| 1 | 77 | 2 | 0 - 1.50 | 0.14 | -- | -- | -- | -- | -- |
| 2 | 233 | 6 | 0 - 8.50 | 0.63 | -- | -- | -- | -- | -- |
| 3 | 293 | 4 | 0 - 11.50 | 1.33 | -- | -- | -- | -- | -- |
| 4 | 11 | 3A | -- | -- | 0 - 45.50 | 19.93 | -- | -- | -- |
| 5 | 64 | 5 | -- | -- | 0 - 25.00 | 6.58 | -- | -- | -- |
| 6 | 277 | 2 | -- | -- | 0 - 13.00 | 3.04 | -- | -- | -- |
| 7 | 319 | 8A | -- | -- | 0 - 5.00 | 1.27 | -- | -- | -- |
| 8 | 8 | 9 | 0 - 1.00 | 0.14 | -- | -- | -- | -- | -- |
| 9 | 8 | 16 | 0 - 1.50 | 0.19 | -- | -- | -- | -- | -- |
| 10 | 9 | 9 | 0 - 1.00 | 0.14 | -- | -- | -- | -- | -- |
| 11 | 12 | 9 | 0 - 2.50 | 0.21 | -- | -- | -- | -- | -- |
| 12 | 18 | 7 | 0 - 3.50 | 0.32 | -- | -- | -- | -- | -- |
| 13 | 18 | 9 | 0 - 1.50 | 0.14 | -- | -- | -- | -- | -- |
| 14 | 18 | 11 | 0 - 2.50 | 0.21 | -- | -- | -- | -- | -- |
| 15 | 18 | 12 | 0 - 6.00 | 0.53 | -- | -- | -- | -- | -- |
| 16 | 19 | 5 | 0 - 3.00 | 0.25 | -- | -- | -- | -- | -- |
| 17 | 40 | 2 | 0 - 1.50 | 0.19 | -- | -- | -- | -- | -- |
| 18 | 87 | 2 | 0 - 2.50 | 0.21 | -- | -- | -- | -- | -- |
| 19 | 87 | 13 | 0 - 6.00 | 0.53 | -- | -- | -- | -- | -- |
| 20 | 87 | 12 | 0 - 11.50 | 1.02 | -- | -- | -- | -- | -- |
| 21 | 102 | 1 | 0 - 7.00 | 0.60 | -- | -- | -- | -- | -- |
| 22 | 102 | 3 | 0 - 8.50 | 0.74 | -- | -- | -- | -- | -- |
| 23 | 119 | 22 | 0 - 10.00 | 0.81 | -- | -- | -- | -- | -- |
| 24 | 121 | 3 | 0 - 3.00 | 0.25 | -- | -- | -- | -- | -- |
| 25 | 126 | 5 | 0 - 8.50 | 0.74 | -- | -- | -- | -- | -- |
| 26 | 126 | 6 | 0 - 4.50 | 0.39 | -- | -- | -- | -- | -- |
| 27 | 201 | 3 | 0 - 13.00 | 0.76 | -- | -- | -- | -- | -- |
| 28 | 231 | 2 | 0 - 7.50 | 0.54 | -- | -- | -- | -- | -- |
| 29 | 235 | 3 | 0 - 6.50 | 0.48 | -- | -- | -- | -- | -- |
| 30 | 235 | 4 | 0 - 5.50 | 0.39 | -- | -- | -- | -- | -- |
| 31 | 251 | 8 | 0 - 12.50 | 0.93 | -- | -- | -- | -- | -- |
| 32 | 256 | 9 | 0 - 11.00 | 0.81 | -- | -- | -- | -- | -- |
| 33 | 267 | 9 | 0 - 15.00 | 0.88 | -- | -- | -- | -- | -- |
| 34 | 277 | 1 | 0 - 10.00 | 0.59 | -- | -- | -- | -- | -- |
| 35 | 279 | 2 | 0 - 4.00 | 0.24 | -- | -- | -- | -- | -- |
| 36 | 281 | 3 | 0 - 14.00 | 0.83 | -- | -- | -- | -- | -- |
| 37 | 293 | 2 | 0 - 21.00 | 2.47 | -- | -- | -- | -- | -- |
| 38 | 297 | 4 | 0 - 17.50 | 2.04 | -- | -- | -- | -- | -- |
| 39 | 311 | 5 | 0 - 9.50 | 0.72 | -- | -- | -- | -- | -- |
| 40 | 313 | 2 | 0 - 22.50 | 1.65 | -- | -- | -- | -- | -- |
| 41 | 314 | 1 | 0 - 13.00 | 0.96 | -- | -- | -- | -- | -- |
| 42 | 323 | 7 | 0 - 6.00 | 0.36 | -- | -- | -- | -- | -- |
| 43 | 9 | 1 | -- | -- | 0 - 26.50 | 6.90 | -- | -- | -- |
| 44 | 22 | 5 | -- | -- | 0 - 54.50 | 14.44 | -- | -- | -- |
| 45 | 35 | 1 | -- | -- | 0 - 18.00 | 4.67 | -- | -- | -- |
| 46 | 39 | 3 | -- | -- | 1 - 4.00 | 27.29 | -- | -- | -- |
| 47 | 40 | 1 | -- | -- | 0 - 53.50 | 14.02 | -- | -- | -- |
| 48 | 40 | 3 | -- | -- | 0 - 13.00 | 3.40 | -- | -- | -- |
| 49 | 46 | 3 | -- | -- | 0 - 42.50 | 11.15 | -- | -- | -- |
| 50 | 62 | 3A | -- | -- | 0 - 52.50 | 13.80 | -- | -- | -- |
| 51 | 67 | 1B | -- | -- | 0 - 32.00 | 8.38 | -- | -- | -- |
| 52 | 76 | 2A | -- | -- | 0 - 7.00 | 1.80 | -- | -- | -- |
| 53 | 76 | 4A | -- | -- | 0 - 43.00 | 11.25 | -- | -- | -- |
| 54 | 80 | 10 | -- | -- | 0 - 10.00 | 2.66 | -- | -- | -- |
| 55 | 82 | 1 | -- | -- | 0 - 17.00 | 4.46 | -- | -- | -- |
| 56 | 83 | 18 | -- | -- | 0 - 1.00 | 0.21 | -- | -- | -- |
| 57 | 83 | 22 | -- | -- | 0 - 1.50 | 0.42 | -- | -- | -- |
| 58 | 83 | 23 | -- | -- | 0 - 1.00 | 0.21 | -- | -- | -- |
| 59 | 84 | 10 | -- | -- | 0 - 13.50 | 4.15 | -- | -- | -- |
| 60 | 92 | 4 | -- | -- | 0 - 18.50 | 4.89 | -- | -- | -- |
| 61 | 107 | 6 | -- | -- | 0 - 17.50 | 4.09 | -- | -- | -- |
| 62 | 107 | 7 | -- | -- | 0 - 42.50 | 10.07 | -- | -- | -- |
| 63 | 108 | 1 | -- | -- | 1 - 31.00 | 30.69 | -- | -- | -- |
| 64 | 113 | 2 | -- | -- | 0 - 25.50 | 5.99 | -- | -- | -- |
| 65 | 124 | 4 | -- | -- | 0 - 10.00 | 2.66 | -- | -- | -- |
| 66 | 122 | 2 | -- | -- | 0 - 12.00 | 3.19 | -- | -- | -- |
| 67 | 124 | 13 | -- | -- | 0 - 15.50 | 4.04 | -- | -- | -- |
| 68 | 133 | 2 | -- | -- | 0 - 16.00 | 4.25 | -- | -- | -- |
| 69 | 145 | 2 | -- | -- | 0 - 85.50 | 22.62 | -- | -- | -- |
| 70 | 149 | 2B | -- | -- | 0 - 48.00 | 12.52 | -- | -- | -- |
| 71 | 151 | 4 | -- | -- | 0 - 45.50 | 12.00 | -- | -- | -- |
| 72 | 153 | 1 | -- | -- | 0 - 50.50 | 13.28 | -- | -- | -- |
| 73 | 162 | 1 | -- | -- | 0 - 98.50 | 25.91 | -- | -- | -- |
| 74 | 208 | 4 | -- | -- | 0 - 5.50 | 1.33 | -- | -- | -- |
| 75 | 233 | 8 | -- | -- | 0 - 51.00 | 13.49 | -- | -- | -- |
| 76 | 235 | 9 | -- | -- | 0 - 25.00 | 6.58 | -- | -- | -- |
| 77 | 236 | 4 | -- | -- | 0 - 5.00 | 1.27 | -- | -- | -- |
| 78 | 236 | 11 | -- | -- | 0 - 9.50 | 2.44 | -- | -- | -- |
| 79 | 237 | 17 | -- | -- | 0 - 1.50 | 0.42 | -- | -- | -- |
| 80 | 238 | 4 | -- | -- | 0 - 41.50 | 10.94 | -- | -- | -- |
| 81 | 238 | 5 | -- | -- | 0 - 43.50 | 11.47 | -- | -- | -- |
| 82 | 239 | 2 | -- | -- | 0 - 95.00 | 24.85 | -- | -- | -- |
| 83 | 244 | 2 | -- | -- | 0 - 47.00 | 12.32 | -- | -- | -- |
| 84 | 246 | 8 | -- | -- | 0 - 7.50 | 1.91 | -- | -- | -- |
| 85 | 246 | 9 | -- | -- | 0 - 7.50 | 1.91 | -- | -- | -- |
| 86 | 255 | 3 | -- | -- | 0 - 44.50 | 11.68 | -- | -- | -- |
| 87 | 259 | 1 | -- | -- | 0 - 45.50 | 12.00 | -- | -- | -- |
| 88 | 260 | 1 | -- | -- | 0 - 50.00 | 13.17 | -- | -- | -- |
| 89 | 268 | 10 | -- | -- | 0 - 4.50 | 1.05 | -- | -- | -- |
| 90 | 268 | 11 | -- | -- | 0 - 11.50 | 2.66 | -- | -- | -- |
| 91 | 270 | 4 | -- | -- | 0 - 63.00 | 14.73 | -- | -- | -- |
| 92 | 273 | 1 | -- | -- | 0 - 41.50 | 9.69 | -- | -- | -- |
| 93 | 277 | 5 | -- | -- | 1 - 11.50 | 29.31 | -- | -- | -- |
| 94 | 277 | 6 | -- | -- | 0 - 45.50 | 12.00 | -- | -- | -- |
| 95 | 281 | 9 | -- | -- | 0 - 5.00 | 1.14 | -- | -- | -- |
| 96 | 282 | 7 | -- | -- | 0 - 11.00 | 2.57 | -- | -- | -- |
| 97 | 302 | 1 | -- | -- | 0 - 50.00 | 13.06 | -- | -- | -- |
| 98 | 313 | 1B | -- | -- | 0 - 12.50 | 3.17 | -- | -- | -- |
| 99 | 316 | 9A | -- | -- | 0 - 0.50 | 0.11 | -- | -- | -- |
| 100 | 319 | 16A | -- | -- | 0 - 8.50 | 2.25 | -- | -- | -- |
| 101 | 326 | 3 | -- | -- | 0 - 44.50 | 11.68 | -- | -- | -- |
| Total | 2 - 95.5 | -- | 20 - 84.5 | -- | -- | -- | -- | ||

1. மேற்கண்ட தகவல் / சான்றிதழ் நகல் விவரங்கள் தமிழ் நிலம் மென்பொருளில் இருந்து (https://eservices.tn.gov.in) பெறப்பட்டவை.
2. இத் தகவல்கள் 28/09/2024அன்று 04:18:25 PM நேரத்தில் அச்சடிக்கப்பட்டது.
3. கைப்பேசி கேமராவின் 2D barcode படிப்பான் மூலம் படித்து 3G/GPRS வழி இணையதளத்தில் சரிபார்க்கவும்.
Need Complete Property Verification?
Get ownership details, EC records, FMB, zone checks, geo-insights & AI analysis - all in one place


Exploring WAQF Land Property in Kallur, Thanjavur
Understanding the WAQF System and Principles of Islamic Endowment
The WAQF system is a cornerstone of Islamic philanthropy, serving as a perpetual endowment dedicated to the welfare of communities. Rooted in Islamic principles, a WAQF involves dedicating assets or property for charitable, religious, or social purposes, ensuring their benefits are preserved for future generations. These endowments often support mosques, schools, orphanages, and other community services.
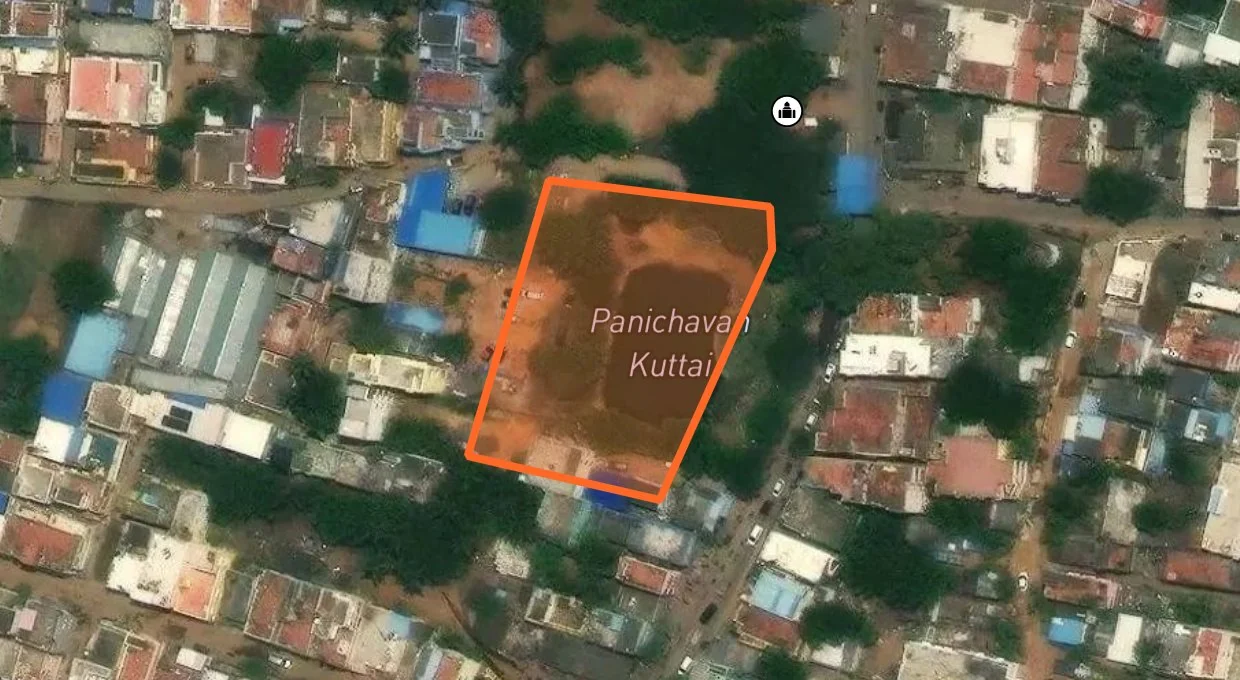
The WAQF land property in Kallur, Thanjavur, stands as a shining example of this enduring tradition. With a total extent of 5000 sq.m, this rural WAQF property (WAQF ID: 483) holds immense potential for societal development while preserving its Islamic heritage.
Legal Framework Governing WAQF Properties
WAQF properties in India are governed by the Waqf Act, 1995, which provides a robust legal framework for the administration, protection, and development of WAQF assets. The Act mandates the registration of WAQF properties under state or central WAQF boards, ensuring their proper management and safeguarding against encroachments.
The WAQF land in Kallur, with its survey number 260, subdivision 1, and patta number 370, falls under this legal framework. Its classification as rural land highlights its potential for agricultural or community-based developments, in line with the objectives of the WAQF system.
Importance of Land Records and Documentation
Accurate land records and documentation are critical for the effective management of WAQF properties. They provide a clear historical account of property ownership, classification, and usage, ensuring transparency and accountability. For the Kallur WAQF property, the detailed records—such as the survey number (260), patta number (370), and total extent (5000 sq.m)—play a pivotal role in its governance.
Meticulous record-keeping helps the WAQF Board and local administrators resolve disputes, prevent illegal encroachments, and implement community welfare projects efficiently. It also reassures stakeholders of the property’s legitimate status and its dedication to charitable purposes.
Survey Numbers: Identifying WAQF Properties
Survey numbers are fundamental to identifying and managing WAQF properties. They serve as unique identifiers in government land records, providing precise details about a property's location, size, and classification. For the Kallur WAQF land, the new survey number 260 ensures its identity is protected within regional land registries.
Subdivision details, such as "Subdivision 1" for this property, further break down larger plots into manageable segments. This allows for effective tracking and monitoring, ensuring that every acre of WAQF land is utilized for its intended purpose.
Community Welfare and Religious Purposes
The primary goal of WAQF properties is to serve the community and fulfill religious obligations. The Kallur WAQF property, with its vast expanse of 5000 sq.m, offers numerous opportunities for community welfare initiatives. Potential uses include establishing schools, healthcare facilities, or agricultural projects that provide sustainable livelihoods for local residents.
Additionally, WAQF properties often support the maintenance of mosques and other religious institutions, fostering spiritual growth and communal harmony. The Kallur property’s rural classification makes it an ideal candidate for projects that align with both community development and Islamic principles.
WAQF Board Administration and Oversight
The administration of WAQF properties falls under the jurisdiction of state and central WAQF boards. These boards are responsible for registering properties, maintaining records, and ensuring their proper utilization. They also oversee the implementation of welfare projects and monitor compliance with the Waqf Act, 1995.
The Tamil Nadu WAQF Board plays a vital role in managing the Kallur WAQF property. By conducting regular inspections and audits, the board ensures that the land's resources are used effectively and that its Islamic endowment principles are upheld.
Heritage Preservation and Maintenance
WAQF properties often carry significant historical and cultural value, serving as tangible links to Islamic heritage. Preserving these assets is crucial not only for their religious importance but also for their role in showcasing the rich history of Islamic endowments.
Efforts to maintain the Kallur WAQF land can include sustainable land management practices, restoration of heritage structures, and the development of facilities that reflect its historical significance. Such initiatives not only honor the intentions of the original donors but also ensure the property remains a valuable asset for future generations.
Legal Protections and Property Rights
WAQF properties enjoy legal protections under Indian law, safeguarding them from unauthorized encroachments and misuse. The Waqf Act, 1995, includes provisions for penalizing those who attempt to infringe upon WAQF lands, ensuring their sanctity is preserved.
The Kallur WAQF property benefits from these legal safeguards, which protect its 5000 sq.m expanse from potential disputes or illegal activities. Property rights are clearly defined in its documentation, including its survey numbers and patta details, enabling swift legal action in case of violations.
Conclusion
The WAQF land property in Kallur, Thanjavur, is a testament to the enduring legacy of Islamic endowments. Spanning 5000 sq.m, this rural property holds tremendous potential for community welfare, religious purposes, and heritage preservation. Through meticulous record-keeping, robust legal protections, and the diligent oversight of the Tamil Nadu WAQF Board, the property continues to serve its noble purpose as envisioned by Islamic principles.
As a vital part of India’s WAQF system, the Kallur property exemplifies the power of philanthropy and endowments in fostering societal development while preserving cultural and religious heritage. Its future lies in the hands of responsible administration, community involvement, and a steadfast commitment to the values that underpin the WAQF tradition.


Ask the records, or walk the map.
LandLens One answers from Tamil Nadu land law itself, cited to the page, then acts on the registers. One Map lights them up on the parcel. Your history stays in one place across both.
YOU APPROVE ANY SPEND
A customer has just used our Building Plan Approval Services
1 hour ago
